01 AML Compliance for UAE Accountants and DNFBPs: goAML Registration, Reporting and Penalties
AML Compliance for UAE Accountants and DNFBPs: goAML Registration, Reporting and Penalties is not a back-office formality. It is a legal and commercial obligation for accountants, auditors, tax advisers, real estate brokers, dealers in precious metals and stones, and other Designated Non-Financial Businesses and Professions operating in the UAE. Owners need to know who must register, what must be reported, and how to avoid penalties. This guide gives a practical route from risk assessment to daily controls.
The main problem is fragmentation: licensing, client onboarding, bookkeeping, VAT, corporate tax, and AML records often sit in different places. When a suspicious transaction appears, staff may not know whether to ask further questions, reject the work, or file a report through goAML. A clear system reduces hesitation.
02 Who is covered under UAE AML rules?
DNFBP status depends on activity, not only on company size. Accounting firms, bookkeeping providers, tax agents, company service providers, real estate professionals, jewellers, and certain consultants can fall within UAE AML obligations when they conduct specified services. If your firm handles client money, forms companies, advises on tax structures, or prepares records used for financial decisions, assume AML duties may apply until confirmed otherwise.
Important: Corporate tax filings are handled with the UAE Federal Tax Authority (FTA) through EmaraTax, but AML registration and suspicious reporting use separate Ministry of Economy and goAML channels. Do not confuse tax compliance with AML compliance.
Common DNFBP examples
Accountants and bookkeepers
They may identify unusual source of funds, unexplained ownership, or transactions inconsistent with recorded business activity.
Company service providers
Formation, registered office, nominee, and management services require beneficial owner checks and ongoing monitoring.
Real estate and asset dealers
High value assets can move wealth quickly, so customer due diligence and payment trail review are critical.
03 goAML registration: what decision makers must organise
goAML is the UAE platform used for suspicious transaction and activity reporting to the Financial Intelligence Unit. Registration is more than creating a username. The business should identify a compliance officer, set internal approval lines, complete prerequisite registrations where required, and keep evidence that the responsible person can access the portal.
For SMEs, the practical owner question is simple: who will receive alerts, review documents, challenge staff, and file quickly if suspicion arises? If that answer is unclear, goAML registration will not protect the business.
Practical registration checklist
- Confirm whether your activity is a DNFBP and document the reasoning.
- Appoint an AML compliance officer or responsible manager with authority.
- Register on required UAE supervisory platforms, then complete goAML access.
- Maintain valid trade licence, passport, Emirates ID, and authorisation documents.
- Test portal access and keep secure credentials with backup coverage.
- Train relevant staff on escalation before accepting high-risk clients.
04 Reporting obligations: when to file and what to keep
A suspicious transaction report is required when there are reasonable grounds to suspect proceeds of crime, terrorism financing, sanctions exposure, or deliberate concealment. You do not need to prove wrongdoing. You need enough reason to believe the matter is suspicious and to preserve confidentiality. Tipping off the client can create additional risk.
Examples include a client refusing to identify beneficial owners, repeated changes to invoices without commercial logic, third-party payments unrelated to the contract, or records that conflict with bank movements. For accountants, mismatches between bookkeeping entries, VAT records, corporate tax working papers, and management explanations should be investigated before submission to the UAE Federal Tax Authority FTA through EmaraTax.
Note: If there is no suspicion but the relationship is higher risk, document enhanced due diligence instead of filing defensively. Poor quality reporting can weaken internal credibility.
Core records to retain
- Client identification, ownership charts, and screening results.
- Risk assessment, approval notes, and changes over time.
- Source of funds and source of wealth evidence where relevant.
- Engagement letters, invoices, accounting records, and payment trails.
- Internal escalation notes and reasons for filing or not filing.
- Training attendance and policy acknowledgements.
05 Building an AML control framework that works
A useful AML framework is proportional. A small remote accounting firm does not need bank-style bureaucracy, but it does need documented risk decisions, consistent client checks, and evidence that reviews happen. Align AML controls with your bookkeeping, VAT, and corporate tax processes so the same facts are not requested repeatedly.
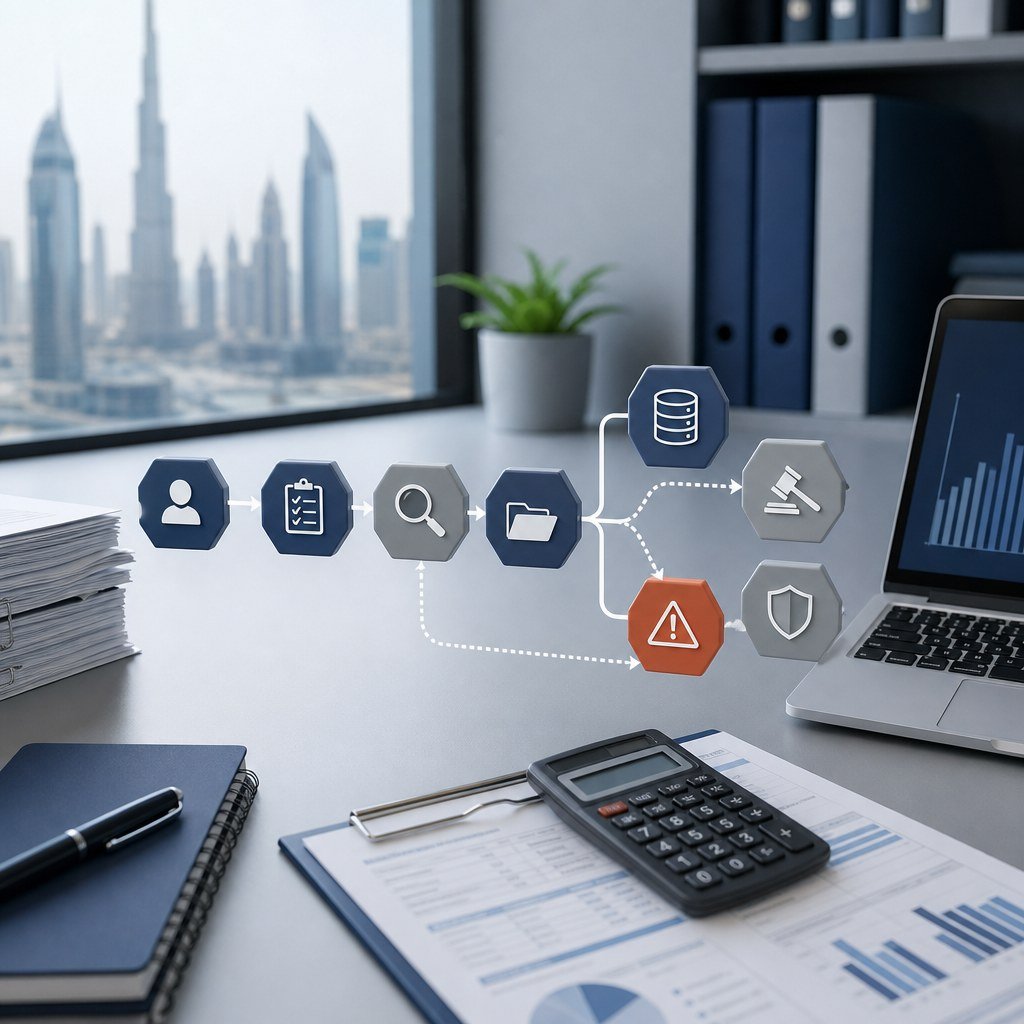
Recommended operating model
The owner or managing partner should review the framework at least when services change, a new high-risk sector is accepted, or a regulator asks for evidence. Treat the review as a business control, not as a legal file stored away.
06 Step-by-step AML compliance execution plan
Use this sequence if your UAE business has limited compliance resources and needs a practical starting point. Adapt it to your licence, services, and risk profile.
- Map services and identify where you act as a DNFBP.
- Create a written AML policy covering onboarding, screening, escalation, records, and training.
- Build a client risk rating form with low, standard, and enhanced categories.
- Collect identity, trade licence, authority, and beneficial owner documents before work starts.
- Screen names against applicable sanctions and adverse information sources.
- Ask source of funds questions when transactions, asset purchases, or funding look unusual.
- Record review outcomes in the accounting file, not only in email threads.
- Escalate concerns internally and decide whether goAML reporting is needed.
- Train finance, sales, and client-facing staff on examples relevant to your industry.
- Schedule periodic file reviews and update risk ratings when facts change.
Important: Do not wait until renewal season or an inspection notice. Retrospective AML files are harder to defend because the business must show what it knew at the time.
07 Common mistakes, risks, and recovery actions
Most AML failures are operational rather than technical. The policy exists, but staff cannot find it; the risk rating is completed once, but never updated; or the compliance officer is named, but has no time or authority. These gaps matter because penalties often focus on whether the business had effective controls, not merely documents.
Mistakes to avoid
- Copying a generic policy that does not match actual services.
- Accepting incomplete beneficial ownership information to keep a client happy.
- Treating cash, crypto, offshore ownership, or complex structures as automatically acceptable.
- Failing to connect AML checks with bookkeeping, VAT, and corporate tax review.
- Using one personal email for goAML access with no continuity plan.
- Discussing a possible report with the client before taking advice.
How to recover
If you discover a gap, act quickly and document the correction. Freeze onboarding for the affected client if necessary, collect missing evidence, update the risk rating, and record who approved the decision. If suspicion exists, escalate without delay. For serious or repeated issues, seek professional advice before contacting the regulator or client.
Business implications can be significant: delayed bank onboarding, refused audits, licence concerns, management distraction, and damaged credibility with counterparties. Strong AML records also support cleaner tax filings because ownership, transactions, and explanations are easier to verify.
08 Penalties and management accountability
UAE AML enforcement can include administrative penalties, remediation directions, restrictions on activities, suspension, cancellation of registration, and referral for criminal investigation where conduct is serious. The exact consequence depends on the facts, the regulator, the breach, and whether management cooperated. Do not rely on informal penalty lists without checking current official guidance.
Decision makers should focus on preventable failures: no risk assessment, no compliance officer, no training, weak due diligence, ignored red flags, poor records, or late reporting. These are the areas an inspector can test through files, emails, and staff interviews.
Note: Penalty exposure is not only a finance issue. Banks, investors, auditors, landlords, and major customers may ask about AML controls before approving a relationship.
09 Summary decision framework
Use a simple three-part test. First, are you performing a DNFBP activity? Second, could your service help move, disguise, or validate funds or ownership? Third, can you prove the checks you performed before accepting or continuing the client? If any answer is uncertain, strengthen controls before the next engagement.
The best option for most SMEs is not over-engineering. It is a lean, written AML process linked to client onboarding, bookkeeping, VAT review, and corporate tax advisory. Where Federal Decree-Law No. 47 of 2022 and FTA decisions affect tax positions, keep tax analysis separate but consistent with AML evidence.
Quick checklist before you accept a client
- Can you identify the true beneficial owners?
- Does the service match the client’s commercial purpose?
- Are payments coming from expected parties and accounts?
- Have sanctions and risk checks been completed?
- Is the file ready for review by management or a regulator?
Suggested meta description: AML Compliance for UAE Accountants and DNFBPs: practical goAML registration, reporting, penalties, and controls for UAE businesses seeking clear next steps.
Contact STH Financial Services
Contact STH Financial Services for practical support with client records, ownership evidence, bookkeeping workflows, VAT, corporate tax, and AML-ready documentation through our accounting and bookkeeping support. We can align files with FTA and EmaraTax needs.