For SMEs, UAE e-invoicing readiness means 3 things: invoice data must meet UAE VAT rules, your accounting system must map it into the UAE Peppol/PINT-AE format, and testing must be completed before go-live. For wider programme context, read STH Financial’s hub on e-invoicing in the UAE; this article focuses on fields, mapping and pre-go-live checks.
01 What SMEs should treat as mandatory before go-live
Do not treat e-invoicing as a PDF replacement. The expected UAE model requires structured invoice data to move through an Accredited Service Provider and the Peppol-based exchange framework, using the UAE implementation of PINT, commonly called PINT-AE.
As checked on 15 November 2026, UAE businesses should separate 3 compliance layers. The invoice must meet Federal Tax Authority VAT invoice rules, the electronic invoice must include the UAE data dictionary and PINT-AE fields, and your process must show that invoices, credit notes, tax treatment and archiving work after go-live.
Start with current VAT tax invoice requirements, then map each field into the structured format. If a field is missing in your accounting software, do not assume your provider can fix it later. Missing TRNs, incomplete addresses, unclear tax categories and manual numbering can all cause validation failures.
02 Core invoice data fields to validate first
FTA VAT invoice requirements remain the starting point. As checked on 15 November 2026, a standard UAE tax invoice should identify the supplier, recipient, supply, tax treatment and amount payable. Confirm the latest FTA wording before final configuration, especially for simplified, export or reverse charge invoices.
Note: A field can be commercially optional today but technically required electronically. If major customers require purchase order numbers, decide whether they are mandatory for those customer groups before testing.
03 How PINT-AE mapping works in practice
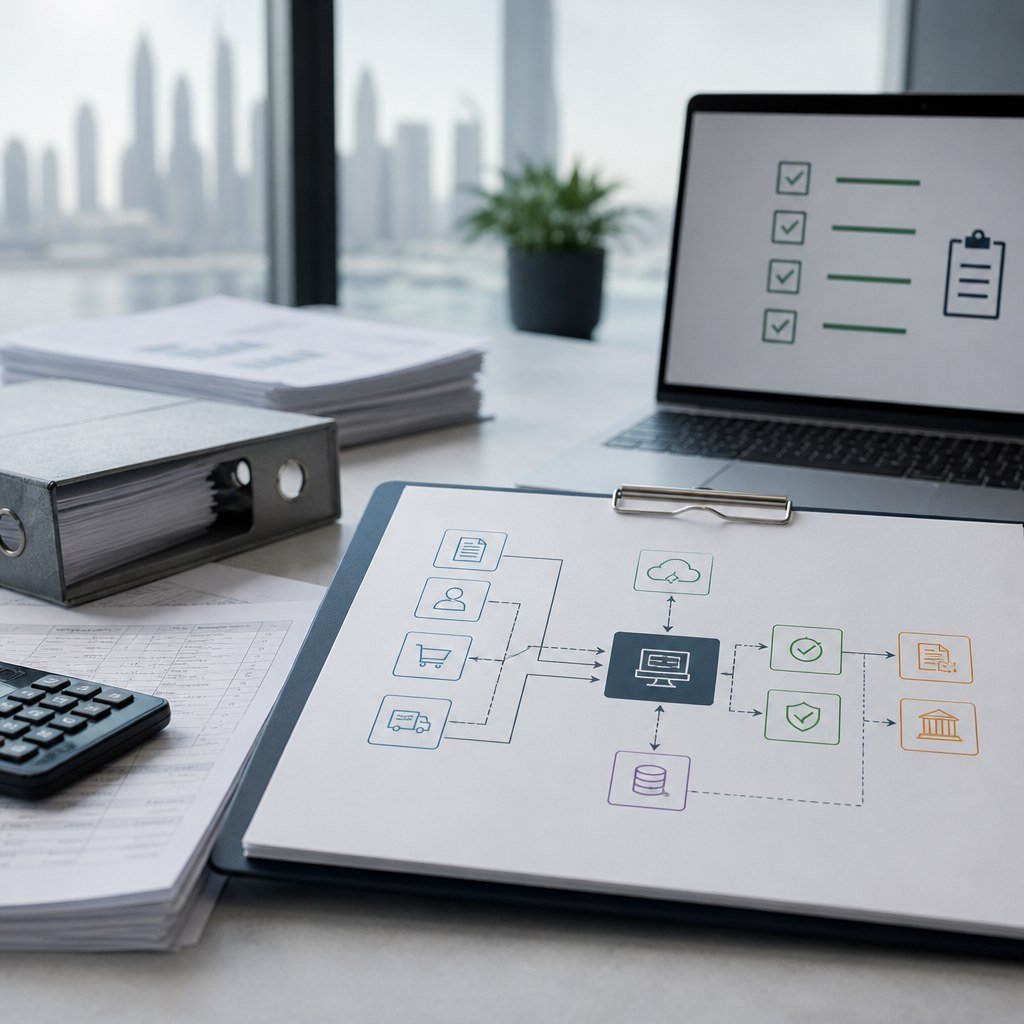
PINT-AE mapping translates your invoice fields into the UAE Peppol invoice structure. Managers do not need XML knowledge, but each business field needs an owner. Ask: where does the field come from, who maintains it, and what happens if it is blank or invalid?
For example, a customer TRN stored in free text may work on a printed invoice but is weak for e-invoicing. Use a validated TRN field on the customer master record, with a control that blocks B2B tax invoices when a required TRN is missing.
Typical source-to-PINT mapping areas
- Invoice type code: Map standard invoices, credit notes and debit notes correctly. Do not use one generic type.
- Party data: Pull seller and buyer details from approved master records, not manual comments.
- VAT category: Distinguish standard-rated, zero-rated, exempt, out-of-scope and reverse charge treatment where applicable.
- Currency handling: Keep transaction currency clear and support VAT reporting amounts in AED where required.
- References: Map purchase orders, contracts, delivery notes and original invoice references for credit notes.
- Allowances and charges: Do not hide discounts, shipping, fees or rebates in one description line if they affect tax values.
Your mapping document should be clear to finance, IT and your provider. Use 5 columns: business field, source system field, PINT-AE target, validation rule and owner. No owner means go-live risk.
04 Edge cases SMEs often miss
Most implementation issues appear outside a simple local sale with 5% VAT. Test your real transaction types, not only one clean invoice.
Credit notes
Each credit note should reference the original invoice and explain the adjustment. Test partial credits, cancellations and VAT-only corrections.
Exports and zero-rating
Zero-rated sales need the correct VAT category and evidence. Do not rely on a description such as “export”.
Reverse charge
Where reverse charge applies, the invoice should identify it clearly. Confirm wording and tax code mapping.
Mixed supplies
If one invoice has different VAT treatments, each line needs the correct category. Header-level tax coding is insufficient.
05 Pre-go-live checklist for your finance team
Use this checklist before approving production access. If you cannot evidence an item, treat it as unfinished.
Master data readiness
- Review supplier legal name, trade name, address and TRN in your accounting system.
- Clean customer names, billing addresses, country codes, TRNs and buyer identifiers.
- Lock critical tax fields so sales staff cannot overwrite them without approval.
- Create a process to onboard new B2B customers with correct e-invoicing details.
System and mapping readiness
- Document every mandatory field and its source system location.
- Run tests for standard sales, credit notes, exports, reverse charge and mixed VAT invoices.
- Confirm that invoice numbering remains sequential and cannot be duplicated.
- Test rejection handling: who receives errors, corrects them and reissues invoices.
VAT and audit readiness
- Reconcile electronic invoice totals to your VAT return working papers.
- Check that VAT amounts in AED are calculated and stored where required.
- Keep evidence for zero-rated and exempt supplies outside the invoice file where necessary.
- Confirm retention, access and backup procedures for structured invoices and records.
Important: Do not leave testing only to IT. Finance should sign off tax codes, invoice samples, credit note scenarios and VAT reconciliation impact before go-live.
06 Common mistakes that delay implementation
The most common mistake is choosing software before cleaning data. A strong provider can transmit structured invoices, but it cannot make poor master data compliant without your rules, owners and controls.
Another issue is treating the PDF as the official output and the structured invoice as secondary. Under e-invoicing, the structured invoice is the compliance object. Check the PDF layout, but focus on the data file and validation result.
Avoid hard-coding today’s tax logic into custom fields without a change process. VAT treatment can vary by supply, customer, place of supply and evidence. Manual descriptions make PINT-AE mapping unreliable.
07 Questions to ask your service provider
Before you sign or configure, ask precise questions. Know where the provider’s role ends and where finance remains accountable.
- Which PINT-AE version and UAE data dictionary release are you configuring against, and what is the release date?
- How will you handle FTA or UAE specification updates after go-live?
- What validation errors will stop invoice exchange, and which errors are only warnings?
- Can we test all our transaction types before production activation?
- How are rejected invoices logged, corrected and resubmitted?
- What audit trail will we have for the original invoice, exchanged file, status response and any correction?
Prepare before validation failures become business delays
Clean invoice data, document PINT-AE mapping and test real scenarios early to make the transition easier.
08 Brief FAQ
Do SMEs need to change their invoice layout?
Possibly, but layout is not the main issue. First ensure the structured data is complete, valid and mapped. Then align the PDF or printed view with customer and VAT presentation needs.
Can you continue issuing invoices if a customer TRN is missing?
It depends on the transaction and customer type. For B2B taxable supplies where the buyer TRN is required, correct the master data before issuing. Add controls so critical fields are not bypassed.
What should you do first?
Start with recent invoices and credit notes. Identify each field, check it against UAE VAT invoice requirements, then map it to PINT-AE with your provider.
09 Summary and next step
E-invoicing readiness depends on accurate VAT data, clean customer and supplier records, documented PINT-AE mapping and tested exception handling. Do not wait until activation to find missing TRNs, weak tax codes or unsupported credit note processes.
Build a field-by-field readiness file for your common invoice types, assign owners and test with your provider. For policy background, timelines and implementation context, continue with STH Financial’s guide to e-invoicing in the UAE.