VAT return filing in Dubai depends on the tax period assigned to your business by the Federal Tax Authority, usually monthly or quarterly. Your practical task is to know the exact period end, file the return and pay any VAT due by the deadline, then keep evidence that supports every figure, especially as invoice data becomes more connected with e-invoicing in the UAE.
01 How VAT return periods work in Dubai
VAT is a federal UAE tax, so the same core filing rules apply to Dubai businesses as they do across the UAE. The FTA assigns your tax period when you register for VAT, and you should confirm it from your VAT registration details in the FTA portal rather than assuming it from your sales cycle.
FTA-sourced fact, checked 7 November 2026: VAT returns are generally filed electronically, and the filing and payment deadline is 28 days after the end of the relevant tax period. If your deadline falls on a weekend or public holiday, you should check the FTA portal and official announcements rather than relying on an internal calendar alone.
Most smaller and mid-sized businesses see quarterly VAT periods, while some businesses may have monthly periods. Monthly filing can improve tax visibility but increases administrative pressure. Quarterly filing reduces frequency but can create larger cash movements and more reconciliation work at period end.
02 Monthly vs quarterly calendar: what changes operationally
The filing rule is simple: calculate the period end, then count 28 days. The operational difference is how often you must close your books, reconcile VAT, review exceptions and submit the return.
Note: Do not build your VAT calendar only from accounting software defaults. Confirm the actual tax period and due date from FTA records, then mirror that date in your finance calendar.
03 What you must prepare before filing
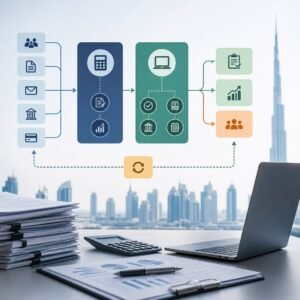
A VAT return is not only a form submission. It is the final output of your sales records, purchase records, tax adjustments and supporting documents. If those records are weak, the return may be filed on time but still expose you to correction work later.
Core documents to reconcile
- Tax invoices issued during the tax period, including credit notes and cancelled invoices.
- Purchase invoices where input VAT is claimed, with supplier TRNs and valid invoice details.
- Zero-rated and exempt supplies, reviewed separately from standard-rated sales.
- Import VAT records, where relevant, matched to customs and accounting entries.
- Output VAT ledger, input VAT ledger and general ledger control accounts.
- Evidence for adjustments, bad debt relief, corrections or reverse charge entries.
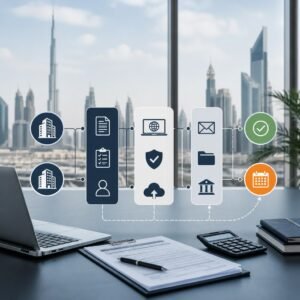
As UAE digital tax administration develops, your VAT process should also consider invoice data quality. Even where your immediate task is VAT return filing, clean invoice fields, clear customer and supplier master data, and consistent tax codes will support future readiness for electronic invoicing requirements.
04 Step-by-step VAT filing checklist
- Confirm the period. Check the FTA portal and record the start date, end date and due date.
- Close sales. Make sure all invoices, credit notes and debit notes for the period are posted.
- Review purchases. Claim input VAT only where you hold valid tax invoices and the expense relates to taxable business activity.
- Run VAT reports. Compare the VAT report with the general ledger, sales register and purchase register.
- Investigate exceptions. Check negative sales, unusual tax codes, missing TRNs and large manual journals.
- Prepare the return. Enter output tax, input tax and adjustments carefully in the FTA return fields.
- Approve internally. Have a responsible manager review the return before submission.
- File and pay. Submit before the deadline and arrange payment early enough for processing.
- Archive evidence. Save the filed return, payment proof, workings and reconciliation files.
05 AED worked example: quarterly VAT payable
Assumption for illustration only: your Dubai trading business files quarterly and all amounts below are standard-rated at 5%, with no exempt supplies or special adjustments.
If the quarter ends on 31 March, the working deadline is 28 April, subject to official calendar confirmation. You should not wait until the last day to pay, because bank processing delays do not remove the obligation to settle by the due date.
06 Late filing and late payment penalties
FTA-sourced penalty position, checked 7 November 2026: a late VAT return filing administrative penalty is generally AED 1,000 for the first occurrence and AED 2,000 for repetition within 24 months. Late payment penalties may also apply where tax due is not paid by the deadline.
You should distinguish between 2 separate failures: filing late and paying late. A business can submit the return but still face payment consequences if the tax amount is not settled on time.
07 Common mistakes and how to recover
Using invoice date cut-offs inconsistently
If sales and purchase teams apply different cut-off logic, your VAT report will not match your accounting close. Set a written rule for period-end posting and apply it consistently.
Claiming input VAT without valid documents
Do not claim input VAT simply because a supplier charged VAT. Check that the invoice is valid, the supplier TRN is captured and the expense is recoverable for your business activity.
Ignoring credit notes
Credit notes change output or input VAT. Match them to the original invoice and ensure they are reflected in the correct period.
Waiting until the 28th day
Last-day filing leaves no room for portal access issues, approval delays or payment processing. Set an internal deadline several working days before the statutory deadline.
Recovery steps after an error
- Identify whether the issue affects tax payable, tax recoverable or classification only.
- Quantify the difference with clear workings.
- Check the applicable FTA correction route, including whether a voluntary disclosure is required.
- Keep evidence of the review, approval and corrective action.
08 Decision framework for business owners
Use this framework to decide whether your VAT process is strong enough:
- If you know your FTA-assigned period and deadline without checking manually each month, your calendar control is working.
- If your VAT report agrees with your ledger before the due date, your accounting close is reliable.
- If you can trace every VAT figure to invoices, credit notes and reconciliations, your evidence file is audit-ready.
- If one person prepares and another reviews the return, your approval control is stronger.
- If your invoice data is structured and consistent, you are better positioned for digital reporting and future e-invoicing processes.
09 FAQ
Is VAT filing in Dubai monthly or quarterly?
It depends on the tax period assigned by the FTA. Do not assume; verify it from your VAT registration details and portal records.
What is the VAT return deadline?
The general deadline is 28 days after the end of the tax period, with payment due by the same deadline. Always check official FTA records for your exact date.
Can you file a VAT return with no sales?
Yes, if you are VAT-registered and a return is due, you must file even where there is no output VAT for the period.
What should you do if you miss the deadline?
File as soon as possible, pay any tax due, download evidence from the portal and review whether penalties or corrections apply.
Keep VAT filing predictable
Before your next VAT period closes, confirm your FTA deadline, reconcile your VAT ledgers and review your invoice data quality. If you want a cleaner process, ask STH Financial to assess your VAT filing calendar, controls and readiness for e-invoicing in the UAE.