A 90-day readiness plan should help you prove 3 things before UAE e-invoicing obligations affect daily billing: your invoice data is clean, your Accredited Service Provider selection is evidence-based, and your team can issue and reconcile test invoices without disruption. Treat the next 90 days as a controlled finance project, not only an IT change.
For wider context, keep your finance team aligned with the main guidance page on e-invoicing in the UAE, then use this plan to focus on the operational work: master data, ASP evaluation, ERP integration, VAT fields, and test scenarios.
01 What you need to be ready for
UAE e-invoicing readiness is not the same as being able to email a PDF invoice. You need structured invoice data, correct VAT treatment, reliable customer and supplier records, and a connection path through an approved or accredited provider model once your business falls within the applicable phase.
As of 8 November 2026, finance teams should verify the latest Federal Tax Authority and Ministry of Finance publications before final sign-off. Public UAE guidance has pointed businesses toward structured electronic invoicing, Accredited Service Providers, and continued VAT compliance. The exact implementation position that applies to you may depend on your entity type, transaction profile, and official phase allocation.
Note: Do not assume your current PDF invoice template is compliant for structured e-invoicing. Use it as a visual output, but test the underlying data fields that will be transmitted, validated, archived, and reconciled.
Your readiness goal is simple: by day 90, you should have a documented data clean-up log, an ASP shortlist with selection reasons, a test invoice pack, exception handling rules, and named owners for tax, finance, IT, and operations.
02 Days 1 to 15: set scope, owners, and source systems
Start with governance. If nobody owns invoice data, VAT mapping, and system testing, the project will drift into last-minute fixes. Appoint one finance lead, one tax reviewer, one system owner, and one decision maker who can approve budget and process changes.
Create a register of all invoicing channels. Include ERP-generated invoices, accounting software invoices, point-of-sale sales, manual invoices, credit notes, debit notes, intercompany invoices, recurring billing, advance payments, and cross-border transactions. If your sales team or operations team can issue commercial documents outside finance, include those documents too.
03 Days 16 to 35: clean customer, supplier, and VAT data
Data clean-up is usually the most valuable part of the 90-day plan. Your ASP and software can only transmit what your records contain. If names, TRNs, addresses, tax codes, product descriptions, and invoice categories are inconsistent, validation errors and reconciliation breaks become likely.
Build a clean-up workbook with 4 tabs: customers, suppliers, products or services, and tax codes. For each record, capture the current value, required correction, owner, evidence source, and completion date. This gives management a clear audit trail and helps you avoid repeated corrections in multiple systems.
Customer and supplier fields to review
- Legal name, trade name, and group company name where different.
- TRN format and whether the TRN belongs to the correct contracting entity.
- Billing address, ship-to address, place of supply indicators, and country codes.
- Email addresses used for notifications, disputes, and remittance advice.
- Customer type: business, government, related party, export, free zone, or consumer where applicable.
VAT and invoice fields to review
- Tax code logic for standard-rated, zero-rated, exempt, out-of-scope, reverse charge, and import-related transactions.
- Invoice line descriptions that are clear enough for customer review and tax substantiation.
- Unit price, discount, taxable value, VAT rate, VAT amount, gross amount, and currency treatment.
- Credit note linkage to the original invoice where your system can store it.
- Rounding rules and decimal handling between your ERP, ASP, and accounting reports.
FTA VAT guidance, checked on 8 November 2026, continues to make prescribed tax invoice particulars important. E-invoicing should therefore be treated as an additional digital control layer, not a replacement for VAT accuracy.
04 Days 36 to 55: map processes before you choose an ASP
Do not select an ASP based only on a demo. First, map your actual invoicing process from contract or order creation to invoice approval, transmission, customer dispute, payment allocation, credit note issue, and VAT return reporting.
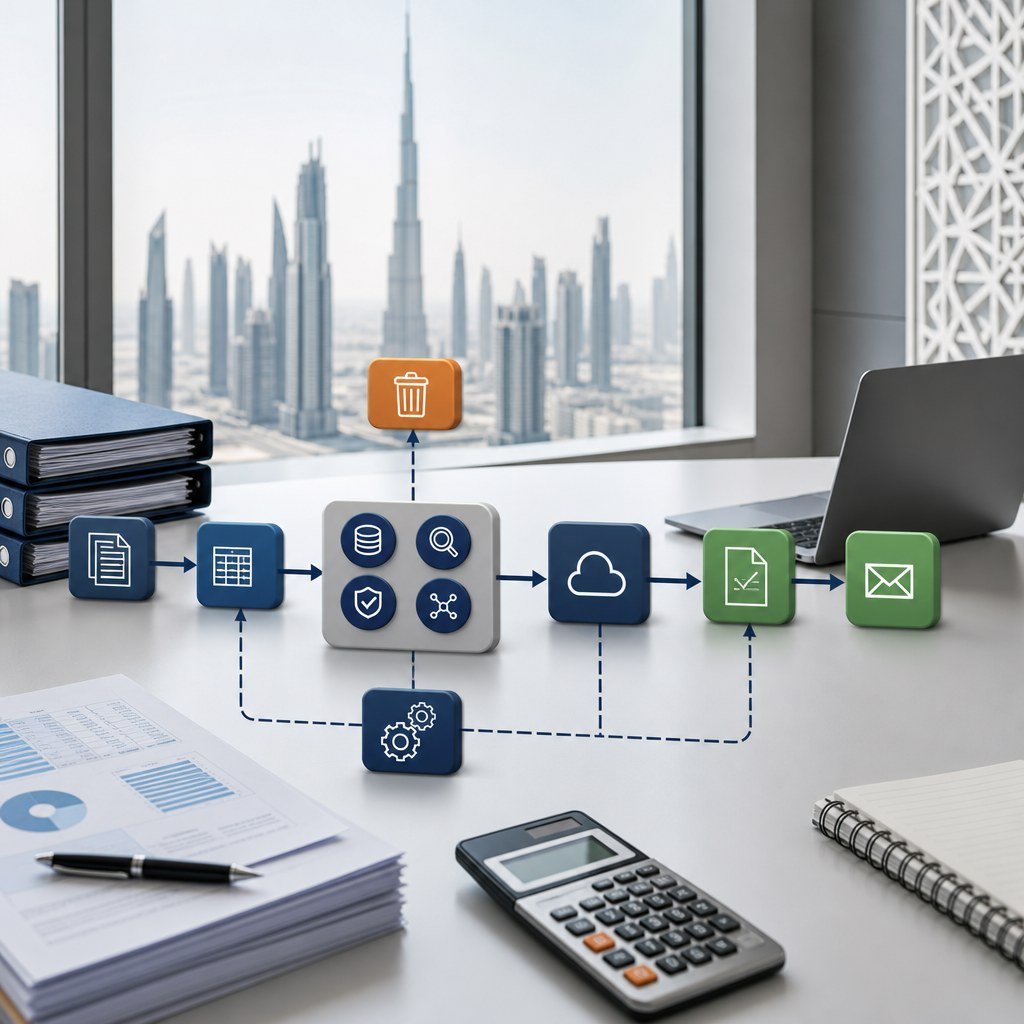
Your map should show where data is created, who approves it, where errors occur, and which reports finance uses at month-end. This is important because an ASP may handle transmission and validation, but your internal controls still determine whether the invoice is commercially and tax correct.
Questions to answer before shortlisting
- Will your ERP connect directly, through middleware, or by file upload during the first phase?
- Can your team handle invoice rejection messages without delaying customer billing?
- Who will monitor transmission status, acknowledgements, and exception queues?
- How will archived e-invoice data reconcile to VAT return workings and financial statements?
- What will you do if the ASP, ERP, or internal approval workflow is temporarily unavailable?
05 Days 56 to 70: select the ASP with evidence, not assumptions
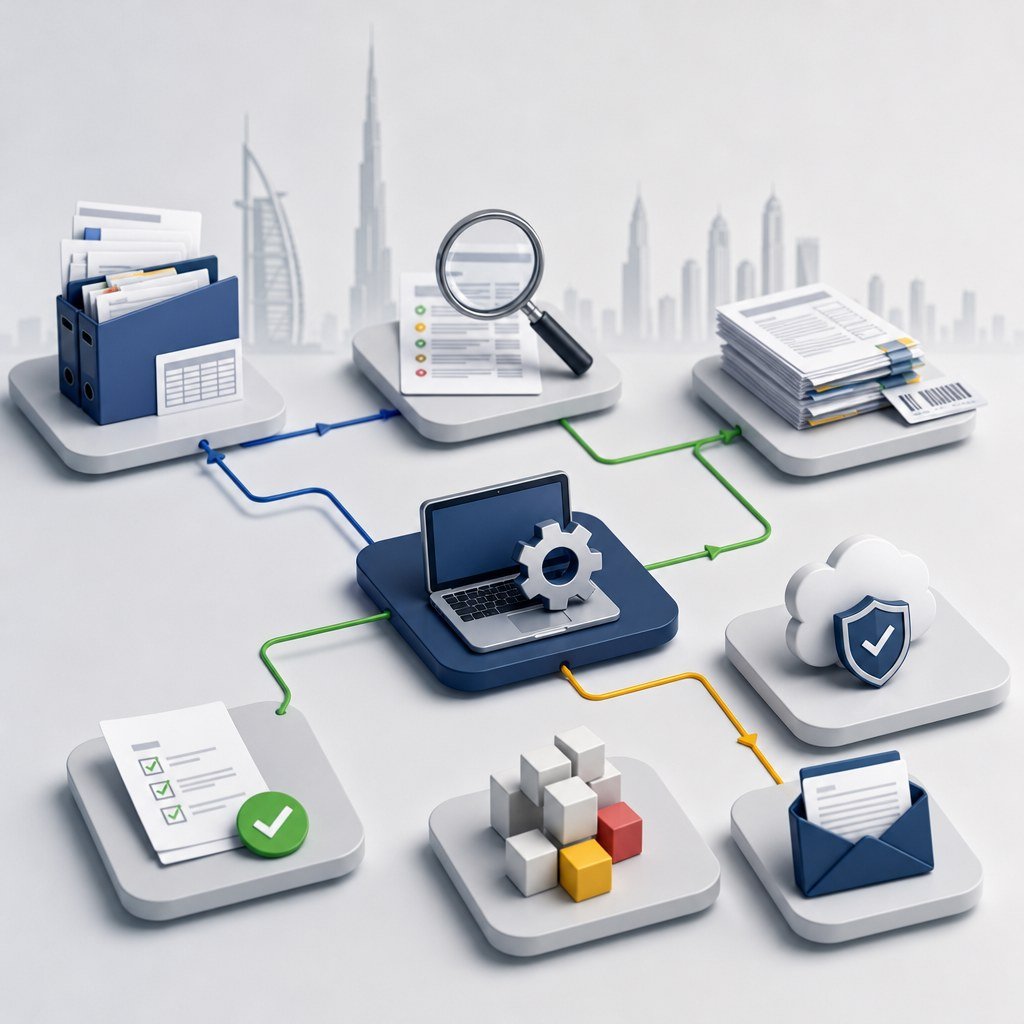
An ASP decision should balance compliance capability, integration fit, service support, data security, and long-term operating cost. Ask each provider to respond to the same checklist so your comparison is fair and defensible.
Accreditation and scope
Confirm current status against official sources. Check whether the service covers your invoice types, entities, currencies, and expected transaction volumes.
Integration approach
Ask for supported APIs, file formats, validation timing, retry logic, sandbox access, and ERP references that match your architecture.
Support and controls
Review support hours, incident escalation, audit logs, user access controls, data retention, and responsibilities during failed submissions.
Request a written responsibility matrix. It should state what the ASP handles, what your ERP partner handles, and what your finance team remains responsible for. This prevents gaps when rejected invoices, duplicate submissions, or tax code errors appear during testing.
06 Days 71 to 90: run test invoices and prove the controls
Your test pack should cover normal invoices and problem cases. If you only test a simple domestic standard-rated invoice, you may miss the issues that create real disruption after go-live. Sector billing patterns matter too: see how UAE retail and e-commerce businesses handle POS sales and returns or how professional services firms bill retainers and milestones under e-invoicing.
Minimum test invoice scenarios
- Standard-rated domestic sale with multiple line items.
- Zero-rated export or qualifying transaction, subject to your tax review.
- Discounted invoice with line-level and document-level discount treatment.
- Credit note linked to a previous invoice.
- Foreign currency invoice and exchange rate handling.
- Related-party or intercompany invoice, if relevant to your group.
- Invoice with missing or incorrect master data to test rejection handling.
- Cancelled, corrected, or reissued invoice scenario based on your internal policy.
For each test, record the input data, expected result, ASP response, ERP posting, customer output, VAT report effect, and exception owner. A test is not complete until finance can explain the accounting and tax outcome, not only the technical status.
Important: Keep test data separate from live customer communications unless your ASP and ERP setup clearly labels the environment. Accidental issue of test documents can create customer confusion and unnecessary correction work.
07 Common mistakes and recovery actions
The most common mistake is delaying data clean-up until after ASP selection. This creates a false sense of progress because the commercial contract moves forward while the finance data remains weak. Recover by freezing new master data creation for a short review period and assigning daily correction targets to data owners.
A second mistake is treating e-invoicing as an IT-only project. Recover by making finance responsible for invoice scenarios, VAT outcomes, and reconciliation evidence. IT should own connectivity and security, but finance should own the business result.
A third mistake is ignoring exception handling. You need a written process for rejected invoices, duplicate invoices, unavailable systems, incorrect TRNs, and customer disputes. Define who can correct data, who approves reissue, and how the correction appears in your accounting records.
Finally, avoid selecting an ASP without checking exit and continuity terms. Ask what happens if your transaction volume changes, your ERP changes, or official requirements are updated. You do not need to predict every change, but you do need a contract and operating model that can adapt.
08 Decision framework for management
At the end of 90 days, management should not ask whether the project “looks ready”. Use a clear decision framework.
- Proceed: data issues are controlled, ASP selection is documented, test invoices pass, and exception owners are trained.
- Proceed with restrictions: simple invoices are ready, but complex scenarios need additional controls or manual review.
- Pause: master data is unreliable, VAT mapping is unresolved, or the ASP integration has not been tested with realistic scenarios.
Your next step is to assign a finance-led readiness owner this week, open the data clean-up workbook, and confirm the latest official requirements before committing to a provider. For ongoing updates and broader planning, refer again to e-invoicing in the UAE and align your internal timetable with official FTA and Ministry of Finance communications.
Need a practical readiness review?
STH Financial can help you review invoice data, VAT mapping, ASP questions, and test invoice scenarios before you move into implementation.